Some political announcements are immediately dramatic.
A government falls. An election is won. A war begins.
Yesterday, seven finance ministers agreed on a number: 15%.
It sounds considerably less exciting.
But the agreement reached by the G7 this weekend could eventually change how some of the world’s largest companies are taxed and, more importantly, says something fascinating about a problem governments have created for themselves.
Companies have globalised faster than taxation has.
For decades, countries have competed to attract businesses by offering lower corporate taxes. Multinational companies, meanwhile, can organise themselves across numerous jurisdictions and report profits in places where taxes are lower.
Individual governments trying to stop this face a basic problem.
Capital can move.
Countries cannot.
Now the G7, Britain, the United States, Canada, France, Germany, Italy and Japan, is trying to change the rules of that competition.
What actually happened?
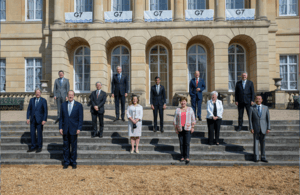
Meeting in London this weekend, G7 finance ministers agreed to support a global minimum corporation tax of at least 15%.
The basic principle is easier to understand than the tax rules themselves.
Suppose a multinational company operates across several countries but records a large proportion of its profits in a jurisdiction where it pays very little tax.
Under the proposed system, extremely low tax rates would become less useful because other countries could potentially collect additional tax until the company’s effective rate reached the global minimum.
The G7 also agreed on another important principle: some of the world’s largest and most profitable multinational companies should pay more tax in countries where they actually conduct business, rather than taxation depending almost entirely on where companies choose to locate their headquarters or intellectual property.
This particularly matters for enormous digital companies.
A technology company does not need to build a giant factory in every country where it has customers. It can sell advertising, subscriptions or digital services across borders while much of the company’s physical infrastructure exists somewhere else.
Tax systems designed when economic activity was easier to locate geographically have struggled to adapt.
Yesterday’s agreement is an attempt to begin doing so.
But it is only a beginning.
Why would countries deliberately lower their taxes?
My first reaction to tax havens used to be fairly straightforward.
If countries allow enormous companies to pay extremely low taxes, close the loopholes.
The problem is that one country’s “loophole” can be another country’s economic strategy.
Imagine two relatively small countries competing for the European headquarters of a multinational company.
Country A charges a corporate tax rate of 25%.
Country B charges 12.5%.
If everything else were equal, Country B suddenly becomes considerably more attractive.
The company brings jobs, investment and some tax revenue with it. Country B may collect a smaller percentage of the company’s profits, but it might be collecting that percentage from economic activity it otherwise would never have attracted.
Country A now has a choice.
It can keep its higher tax rate and risk losing investment.
Or it can lower its own rate.
Then Country C responds.
This creates what critics describe as a race to the bottom: governments repeatedly reduce corporate taxes because each fears that maintaining higher rates will push investment somewhere else.
The strange result is that governments which individually want to tax companies more may collectively find themselves unable to do it.
That is why the G7 agreement matters.
It is an attempt to transform taxation from a competition into a coordination problem.
If everyone agrees on a floor, nobody needs to be as frightened of being undercut.
At least, that is the theory.
But 15% is not particularly high
There is an obvious criticism.
Fifteen per cent is still a fairly low corporate tax rate.
President Biden’s administration originally supported a global minimum of 21%, before negotiations moved towards the lower figure.
That compromise tells us something about international agreements.
The strongest agreement imaginable is useless if nobody signs it.
The weakest agreement imaginable is useless even if everybody does.
International negotiations therefore happen somewhere between ambition and participation.
A 21% minimum might collect more revenue and do more to reduce tax competition. A 15% minimum may attract broader international support.
Which is better depends partly on whether the alternative to 15% is 21% — or nothing.
That distinction seems obvious, but political debates frequently ignore it.
Policies are compared with perfection rather than with the realistic alternatives governments actually possess.
The sovereignty problem
There is also a legitimate argument against the proposal.
Why shouldn’t countries decide their own tax rates?
Taxation is one of the most fundamental powers of a government. Different countries have different economic models.
A smaller economy may reasonably decide that lower corporate taxes are necessary to compensate for disadvantages such as a smaller domestic market.
If seven wealthy countries establish a minimum rate and then pressure everybody else to accept it, smaller states may understandably ask whose interests the new system actually serves.
The G7 represents some of the world’s largest advanced economies.
It does not represent the world.
Ireland, for example, is not sitting at the G7 table. Neither are most developing countries.
India isn’t either.
That does not automatically make the agreement illegitimate. The G7 countries are trying to establish common ground before taking the proposal into wider negotiations.
But the distinction matters.
Calling something a global tax agreement does not make it global.
Not yet.
For that, much broader agreement will be required through the G20 and negotiations involving many more countries.
India has an interesting position
For India, the second part of the agreement may be particularly significant.
India has an enormous and increasingly digital consumer market. Companies can earn considerable revenue from Indian users without necessarily having the same physical presence that a traditional company would require.
India has already introduced an equalisation levy affecting certain digital services partly because existing international tax rules have struggled with this problem.
Other countries have introduced their own digital taxes too.
The United States dislikes many of these measures because they disproportionately affect large American technology companies.
That has created the possibility of something absurd.
Countries introduce digital taxes because they believe multinational companies are not paying enough.
America threatens trade measures because it believes those taxes unfairly target American companies.
Other governments threaten retaliation.
A disagreement about how to tax Google can eventually become a disagreement about tariffs on completely unrelated products.
The G7 proposal offers a possible escape.
Instead of every country inventing its own tax and provoking retaliation, governments could agree on common rules determining where profits should be taxed.
That would be much cleaner.
Whether countries can actually agree on those rules is another question.
This is really about power
Taxes sound like economics.
But this agreement is fundamentally political.
For most people, governments possess enormous power.
If I earn income in India, I cannot announce that I would prefer to be taxed according to the laws of another country because its rate is lower.
A multinational corporation has considerably more flexibility.
It can decide where to invest.
It can organise subsidiaries across jurisdictions.
Intellectual property can be located separately from customers.
Profits can cross borders far more easily than ordinary taxpayers can.
That creates an imbalance.
Governments remain geographically fixed while the organisations they are trying to regulate increasingly are not.
The 15% proposal is therefore an attempt by governments to recover some of the bargaining power that globalisation has taken away from them.
And they can only recover it through cooperation.
One government acting alone risks losing investment.
Several large governments acting together can change the incentives.
Nearly every major international problem seems eventually to arrive at the same difficulty:
cooperation is most necessary precisely when individual countries have an incentive not to cooperate.
Who actually pays a corporate tax?
There is another reason I am hesitant to describe this simply as governments versus giant corporations.
Companies are not people, but the economic consequences of taxing them eventually reach people.
Higher corporate taxes may reduce profits received by shareholders.
They may reduce investment.
Companies may pass some costs onto consumers through higher prices or onto workers through wages.
Alternatively, governments may collect billions in additional revenue and spend it on healthcare, education, infrastructure or reducing other taxes.
The final effect depends on how companies respond and what governments do with the money.
So “make corporations pay their fair share” is politically powerful language, but it does not answer the economic question.
What is the fair share?
And who ultimately bears it?
Those are much harder questions.
The biggest obstacle comes next
The photographs from London make this weekend look like a completed agreement.
It isn’t.
Seven countries agreeing among themselves is relatively easy compared with persuading the rest of the world.
The proposal now has to move into broader negotiations, including the G20.
Countries that benefit from low corporate taxes may resist.
Developing countries may demand a greater share of taxing rights.
The United States will have to translate an international agreement into domestic political action.
And companies will adapt to whatever rules governments eventually create.
Tax avoidance is partly a legal problem, but it is also a permanent contest between regulation and innovation. Change the rule and accountants discover how the new rule works. Governments respond. Companies respond again.
There probably isn’t a final move.
Why this agreement matters anyway
Despite all those limitations, I think yesterday matters.
Not because 15% is magically the correct corporate tax rate.
I have no idea whether it is.
What seems more important is the principle behind it.
For several decades, governments have responded to globalisation partly by competing with one another for mobile companies and investment.
This agreement attempts something different.
Instead of asking:
“How can our country become more attractive than theirs?”
the governments are asking:
“Is there a minimum standard below which none of us should compete?”
That is a significant change.
But it also creates a responsibility.
If wealthy countries are going to cooperate to prevent corporations moving profits towards jurisdictions offering them better terms, they cannot simultaneously design international rules that simply move more tax revenue towards wealthy countries.
Developing economies need investment too.
Smaller countries need ways to compete too.
And governments outside the G7 deserve influence over rules they will be expected to follow.
The real test of this agreement will therefore not be whether seven finance ministers can agree on 15%.
It will be whether countries with completely different interests can be persuaded that following the same rules leaves them better off than competing against each other.
I used to think political power mostly meant the ability to make other people do something.
Increasingly, I think some of the most interesting forms of power work differently.
Sometimes power is the ability to create a system in which everybody decides that cooperating is better than cheating.
That is much harder.
But if this agreement survives what comes next, it may also be much more important.

